EPIC CONSTRUCTION MANAGEMENT LLC
Building today for tomorrow.
- SUPPORTING DETAIL
Economics Snapshot
Original model versus an unverified negotiation target
The original case does not meet the assumed 8.50% NOI-yield hurdle. Rev B tests ways to improve the arithmetic; it does not verify lower construction costs, higher achievable rents, committed occupancy or investor returns.
Source basis: September 9, 2026 planning package · Not independently re-underwritten.
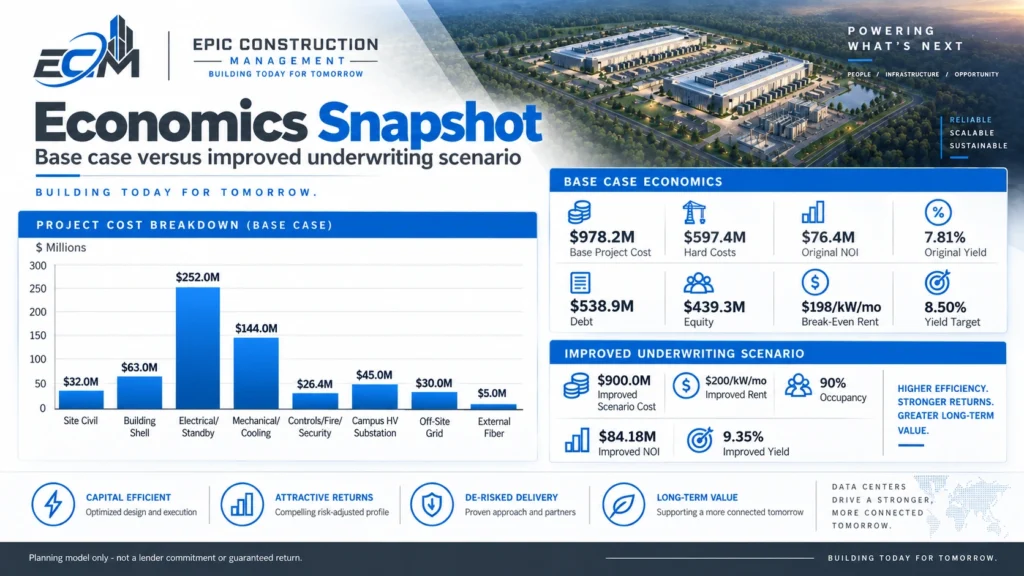
- CLARIFICATION: $198/kW/month means rent to meet the 8.50% yield hurdle, NOT operating break-even. The $900m / 9.35% case is an unverified target.
7.81%
Original NOI yield
8.50%
Illustrative hurdle
9.35%
Unverified target-case yield
Planning data & boundaries
| Annual stabilized metric | Original case | Negotiation target | Downside stress |
|---|---|---|---|
Total modeled cost |
$978.164m |
$900.000m |
$990.000m |
Capacity rent / kW / month |
$185 |
$200 |
$185 |
Paid capacity occupancy |
90% |
90% |
80% |
Capacity revenue |
$95.904m |
$103.680m |
$85.248m |
Non-power operating expense |
$19.500m |
$19.500m |
$19.500m |
Net operating income |
$76.404m |
$84.180m |
$65.748m |
NOI / total modeled cost |
7.81% |
9.35% |
6.64% |
NOI calculation and return definition
Original annual capacity revenue is 48,000 kW x $185 x 12 months x 90% = $95.904 million. Subtracting $19.5 million of modeled non-power operating expense gives $76.404 million NOI. Electricity reimbursed at cost is omitted from both sides. NOI yield is not project IRR, equity IRR or distributable cash.
Correct interpretation of the $198 label
At the original cost and 90% paid occupancy, approximately $198.0015 per kW per month is needed to reach the 8.50% NOI-yield hurdle. It is NOT an operating break-even rent. The source graphic uses an abbreviated “Break-Even Rent” label; this clarification controls its interpretation.
What the target actually changes
The target tests a $900 million scope-matched facility cost and $200 capacity rent, holding paid occupancy and non-power operating expense constant. The implied $78.164 million cost reduction is not an evidenced saving. Additional energy, IT, recovery and unpriced utility exposure cannot be added without retesting returns and liquidity.
Cash flow and funding remain separate
Original modeled debt is approximately $538.9 million and equity $439.3 million. Rev B holds original annual debt service constant for sensitivity comparison, rather than resizing debt. Replacement reserves, debt service, financing, actual lease-up deficits, tax and an eventual exit all require separate treatment before investor-return claims.
Source trail
- Original prospectus: slides 35-38.
- Original model: Capex; Operating.
- Rev B model: Inputs; Yield_Cases; Budget_Boundaries.
- Original document names and publication boundaries are listed in the source register.